Protests, reforms and France: rising debt costs threaten economic stability as borrowing pressures mount
Education plans meet debt pressure
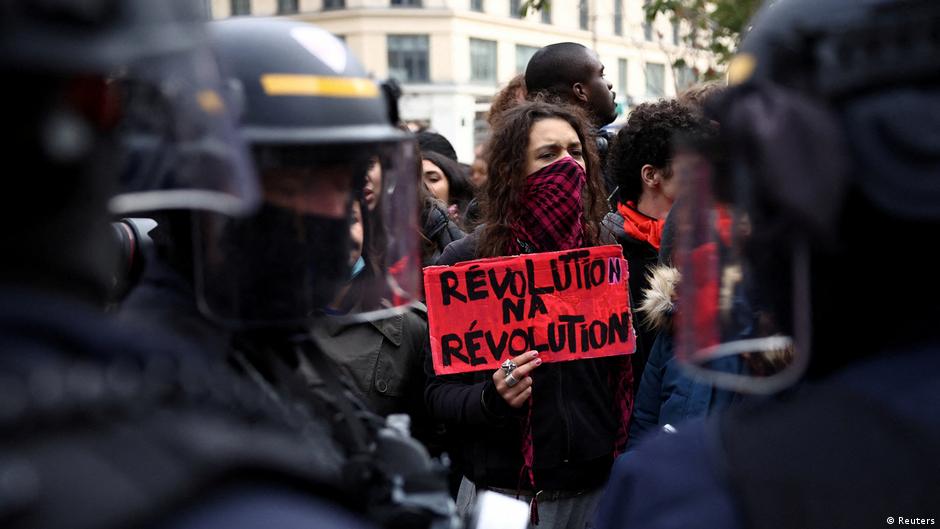
The government plans to provide €4 billion in low-interest loans to renovate schools by 2030, alongside another €1 billion for universities by 2029. The proposals come amid nationwide protests and a difficult political standoff.
France’s public debt is around 120% of GDP, compared with roughly 65% in Germany. France has run budget deficits for decades; the last balanced national budget was in 1974.
Investors demand higher returns
France’s credit rating is lower than Germany’s, and some agencies have given France a negative outlook. The country pays nearly 1.6 percentage points more than Germany on 10-year bonds, with the gap at its highest since the financial crisis.
Interest bills expected to climb
France is expected to pay more than €79 billion in interest on public debt in 2026. The projected cost rises to over €91 billion in 2027 and could reach €125 billion to €132 billion by 2030.
Those totals include social security funds and local authorities, while the central government’s interest bill is estimated at €62.6 billion. France must also refinance bonds issued when rates were historically low and borrow more to cover its budget deficit.
Political choices remain difficult
Heinemann warned that a sharply widening spread could raise borrowing costs for people and put pressure on banks. He said the situation could move toward a financial crisis if the country did not change course.
Key points
- France plans €5 billion in education funding amid nationwide protests.
- Public debt stands at around 120% of GDP, compared with roughly 65% in Germany.
- France pays nearly 1.6 percentage points more than Germany on 10-year bonds.
- Public-debt interest costs could reach €125 billion to €132 billion by 2030.